Which financial check is the casino talking about?
| Check | Main question it addresses | What the customer may notice |
|---|---|---|
| Age and identity verification | Who is using the account, and are they old enough? | Electronic matching or a request for suitable ID. |
| Financial vulnerability check (FVC) | Do public records show significant financial vulnerability? | A background public-record check; a result may lead to contact or proportionate action. |
| Operator-led affordability assessment | Does the operator have concerns about gambling and financial circumstances? | Questions, an assessment or financial-document requests under its process. |
| Source-of-funds check | Where did money for particular activity come from? | Evidence connecting funds to their legitimate source. |
| Financial risk assessment (FRA) | What does limited credit-reference information indicate about financial difficulties? | A separately announced staged regime; do not substitute its planned thresholds for the current FVC rule. |
The same person can encounter more than one check. A request for a bank statement does not establish that the £150 FVC requires everyone to upload one. The Commission’s October 2026 research explicitly distinguishes company-led checks, public-record FVCs and source-of-funds checks, and notes that people often confuse them.
This guide concerns adults using online casinos licensed for Great Britain. It is not a single set of rules for every UK gambling product or a statement that every operator follows the same internal process.
What is the current £150 financial vulnerability threshold?
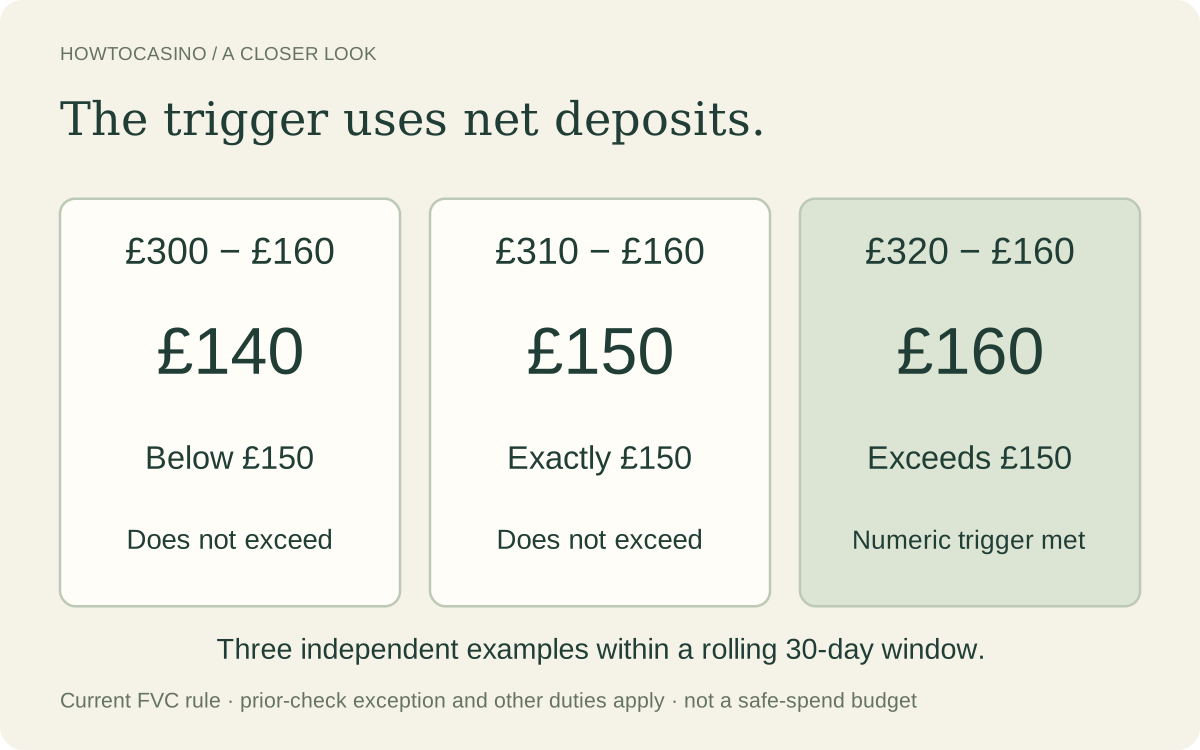
LCCP 3.4.4 sets the relevant FVC threshold as deposits minus withdrawals exceeding £150 in a rolling 30-day period, from 28 February 2025. It is a net-deposit calculation at the operator, not total bets placed, a calendar-month allowance or a measure of what you have lost.
| Independent example within the relevant window | Deposits minus withdrawals | Does the number exceed £150? |
|---|---|---|
| £300 deposited; £160 withdrawn | £140 | No |
| £310 deposited; £160 withdrawn | £150 | No: exactly £150 does not exceed it |
| £320 deposited; £160 withdrawn | £160 | Yes: subject to the rule’s prior-check exception |
These figures explain the calculation, not an amount it is safe to gamble. An operator may need to act on other information below the threshold. The calculation also does not tell you whether a payment still pending has been treated as a completed withdrawal: use the transaction status and ask the operator to explain its ledger.
“Rolling” means looking back over the relevant period as it moves, rather than resetting everything on the first of a month. For a disputed calculation, ask for the window’s start and end times and which deposits and withdrawals were counted. Comparing a calendar-month bank statement with a rolling account total may otherwise produce different answers.
Does the casino have to repeat the check every time?
The current wording of paragraph 5 of LCCP 3.4.4 says the threshold does not require another FVC if the operator has conducted an FVC or FRA within the previous 12 months. That exception does not remove its wider customer-interaction or anti-money-laundering duties.
The FVC looks for significant public-record events such as bankruptcy, judgments and formal debt arrangements. A flagged record is information to assess with the other permitted information about the customer; it is not a universal instruction to close every account with a CCJ.
Will I have to provide bank statements or payslips?
The FVC itself is a public-record check and does not require customers to supply documents for that check. If it identifies a concern, the operator may separately contact the customer or seek financial information where appropriate. Operator-led affordability reviews can also involve documents.
Source of funds is a different question. A bank statement, payslip or sale record may be requested to establish where particular money came from. Having enough money in an account does not, on its own, explain its source; a salary document alone may not show how the money reached the payment account used.
- Ask which check is being conducted and what question each requested document is intended to answer.
- Ask for acceptable alternatives if you do not hold the particular document named.
- Check the privacy notice and use the operator’s official secure upload process.
- If redaction is needed, ask what may be obscured before submitting; removing the necessary evidence may prevent the check being completed.
- Keep a record of submission, any rejection reason and the next requested step.
The Commission says information should be requested promptly when needed, rather than held back until a withdrawal. Later legal obligations can still justify a new request. Our ID guide explains that distinction; being verified at registration does not certify all future money movements.
Will an affordability check affect my credit score?
Check the named search and its purpose. Sky Betting & Gaming describes its affordability process as a TransUnion soft search that leaves a footprint visible on the customer’s file without affecting the credit score or credit approval. William Hill likewise says its described affordability check does not affect the score but may appear as a search.
Those are statements about the checks those businesses describe. A search entry, a bank-statement gambling transaction and debt used to fund gambling are different things. A statement that one check is a soft search does not establish how a lender will assess the rest of an application.
If an entry seems wrong, identify the business, credit reference agency, date and search category first. Ask the relevant organisations to investigate the mismatch. Our credit reports and bank statements guide explains why a casino-related search is not the same as an account debt.
Are financial risk assessments already the same as the £150 check?
No. On 7 July 2026 the Commission announced a staged introduction of FRAs, using limited credit-reference information for higher-spending accounts. The announcement left the first start date to a later implementation document. Its report published on 20 October 2026 still describes FRAs as not yet implemented. These are dated regulatory statements, not evidence that every operator is already applying the final thresholds.
| Announced stage, not a universal current trigger | Age 25 and over | High-risk group, including under 25 |
|---|---|---|
| First stage: largest operators | Exceeds £5,000 net deposits in rolling 24 hours | Exceeds £2,500 in rolling 24 hours |
| Final stage, when implemented | Exceeds £1,000 in rolling 24 hours OR £3,000 in rolling 90 days | Exceeds £750 in rolling 24 hours OR £2,000 in rolling 90 days |
The July plan describes document-free credit-reference assessments, with no credit-score effect, while allowing further appropriate steps where matching fails or risks need addressing. It is not a promise that no operator will ever request documents. The interim stages and timetable require their own published confirmation.
If a notice uses “FRA”, ask which implemented policy, date and threshold it relies on. Do not use an old pilot article, this planned-stage table or a casino’s generic affordability page as proof of the rules applied to a specific account.
What if the check leads to a limit or suspension?
Ask for the type of check, what action has been taken, any information still needed and how to request a review. Under the FVC code, action must be proportionate to the risk considered. Where action decisions are fully automated, the code requires the opportunity for manual review.
Keep the restriction, data question and money record separate. A deposit limit does not explain the status of a withdrawal. Our suspended account guide shows what to record and which questions to put to support.
If you dispute a decision, use the operator’s formal complaint route and retain its response. The appropriate next step depends on whether the dispute concerns a gambling transaction, inaccurate data or another issue. A financial check is not a reason to move to an unlicensed site or bypass self-exclusion.
Related questions
Is the £150 check based on deposits or losses?
It uses deposits minus withdrawals over a rolling 30 days, not losses or total stakes. Those figures can differ substantially: money can be deposited without yet being gambled. The prior-check exception and other regulatory duties still apply.
Does a CCJ mean my casino account must close?
The public-record result must be assessed with the other permitted information and followed by proportionate action. It is not a universal automatic-closure rule for every CCJ. Ask what action was taken in your case and how to request a review.
Can I refuse to provide financial documents?
You can question a request, ask its purpose and seek acceptable alternatives. Refusing does not guarantee continued account use or immediate payment: an unresolved legitimate check can affect what the operator can do. Ask separately about restrictions, funds and its complaint procedure.