Who operates Paddy Power’s casino services?
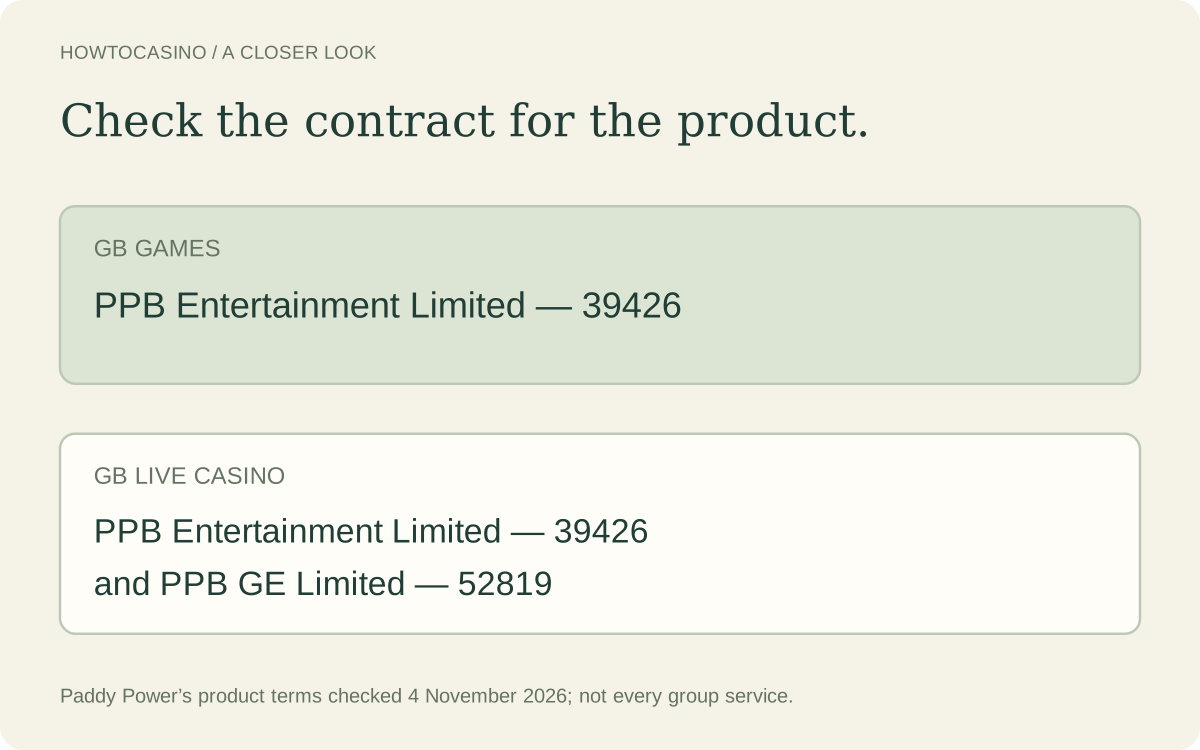
Paddy Power’s additional terms name PPB Entertainment Limited as the UK Games supplier, and PPB GE Limited with PPB Entertainment Limited for UK Live Casino.
| Company | UKGC account | Register finding on 4 November 2026 |
|---|---|---|
| PPB Entertainment Limited | 39426 | Active remote Casino; www.paddypower.com Active. |
| PPB GE Limited | 52819 | Active remote Casino; www.paddypower.com Active. |
| PPB Games Limited | 39411 | Active remote Casino; www.paddypower.com Active. |
PPB Games Limited is also named in the general terms. Its name alone does not make it the supplier for the Games tab. The sportsbook company PPB Counterparty Services Limited has a different role.
This Paddy Power Casino review covers the GB Games and Live Casino arrangements. A licence establishes permission; it does not establish access to every game or guarantee an individual payment.
What is useful, and what needs checking?
| Documented feature | Practical benefit | Important limit |
|---|---|---|
| Different bank-payment routes | Pay by Bank has a published £5 deposit floor, lower than the £30 standard-bank-transfer floor. | Use the matching route in the cashier; the two are not interchangeable. |
| High Protection trust arrangements | The operator describes how customer money is separated through a trust. | Some money in transit through payment providers is outside that trust temporarily. |
| No inactive-account fee | Leaving the account unused does not itself produce the dormant-account charge described by some other operators. | Dormant accounts can still be reclassified or deleted under the account terms. |
| Published withdrawal and complaint help | There is a documented path for checking a payment and escalating a dispute. | Published timings are conditional descriptions, not our payment-test results. |
The main choice is whether the documented payment route and account conditions meet your needs. We have not scored the casino, tested its app or support, or counted its current games. A known name is useful for finding the right records; it is not a reason to overlook the conditions below.
Which payment methods and minimums are documented?
Paddy Power’s deposit help lists debit cards, Apple Pay, PayPal, Skrill, Neteller, Pay by Bank and standard bank transfer, among other methods. It says the country-appropriate alternatives appear in the cashier. A deposit listing does not by itself prove that the same method can receive a withdrawal.
| Route | Published minimums | Conditions or unknowns |
|---|---|---|
| Pay by Bank | Deposit £5; withdrawal £0.01 | UK users need GBP as the account currency and an eligible UK sterling bank account. First-use and withdrawal conditions apply. |
| Standard bank transfer | Deposit £30; withdrawal £10 | A separate route from Pay by Bank, with different transfer times. Check the daily limit shown before sending money. |
| Debit card | GBP deposit minimum not established in the text reviewed | Deposit and withdrawal support are documented. The card must support the applicable withdrawal route. |
| Apple Pay | GBP deposit minimum not established in the text reviewed | Withdrawals require a card previously used to deposit through Apple Pay on the Paddy Power account. |
| PayPal | GBP deposit minimum not established in the text reviewed | The official help documents deposits and withdrawals. Net-deposit routing can restrict the destination. |
| Skrill and Neteller | GBP deposit minimum not established in the text reviewed | The help documents these e-wallets; check the available withdrawal method and its conditions in your own cashier. |
The bank-transfer comparison supplies the £5/£30 and £0.01/£10 figures above. It is not evidence of a £5 minimum for every Paddy Power deposit. The deposit help directs customers to the amount and payment-information fields for the method they select.
A payment minimum is also different from the deposit or staking needed for a promotion. We have not included a current welcome offer. If you accept one, read its eligibility, time limits, qualifying payment methods and withdrawal conditions separately.
How long do Paddy Power withdrawals take?
There are several published timing descriptions. Match the method and first-use conditions before relying on one. Being able to submit a request, finishing an account check and seeing money in a bank account are different events.
| Route | Published description | How to interpret it |
|---|---|---|
| Pay by Bank | The dedicated page asks customers to allow at least 90 minutes for a first withdrawal; later withdrawals should be instant. | Eligible bank and account required. Rare delays are acknowledged; the page says to contact support if funds are still missing after 24 hours. |
| Eligible card instant withdrawals | The withdrawal guide says 1–4 hours for Visa and participating Mastercard cards, with longer cases possible. | Eligibility matters. This is not a promise that every debit-card withdrawal arrives in four hours. |
| Standard card withdrawals | The guide gives 2–5 working days from the request. | Bank holidays are excluded. The method shown at confirmation matters more than an instant-payment headline. |
| Standard bank transfer | The bank-transfer guide gives 1–5 days; the payment FAQ separately describes a UK GBP cut-off of 10.30am for same-day versus next-day arrival. | The pages use different levels of detail. Do not treat the shorter statement as a universal promise or add the periods together. |
| PayPal and Neteller | The payment FAQ says processing can take up to 24 hours during busy periods. | A published processing statement is not an account-specific arrival guarantee. |
The broad bank-transfer page also describes later Pay by Bank payments as immediate. The dedicated Pay by Bank page makes the first-withdrawal allowance explicit. Its separate restriction of up to 24 hours after a first deposit is labelled for Irish customers; it should not be presented as a blanket GB rule.
The payment FAQ mentions up to two hours for some eligible Visa cards, alongside longer standard-card windows. We retain the eligibility distinction rather than choosing the shortest number. Check your request confirmation and any outstanding verification message, then use the relevant help page if the payment is overdue.
Why can the withdrawal destination be restricted?
Paddy Power’s net-deposit policy tracks deposits minus withdrawals for each payment method. Before you send additional money to a preferred method, you may need to return the outstanding deposited amount to another method first. This is about routing available money, not a wagering target.
| Invented account history | Deposited | Already withdrawn | Outstanding net deposit |
|---|---|---|---|
| Debit card | £60 | £20 | £40 |
| PayPal | £30 | £10 | £20 |
Assume this account has £100 available to withdraw and the customer wants to withdraw £70 in total, preferably to PayPal. Applying that policy to this invented example, the outstanding £40 card deposit must first go back to the card. The remaining £30 of that £70 request can then go to PayPal. That leaves £30 in the casino account. This assumes the methods are eligible and there are no other restrictions.
If a card is expired, closed or no longer yours, ask support how to resolve the payment record. Do not make another deposit or place bets to try to fix a routing problem.
How are customer funds protected?
Paddy Power describes a High Protection arrangement using The Sporting Exchange (Clients) Limited as trustee. Its published Trust Deed is dated 19 April 2024. The purpose is to hold customer funds separately from the operating business, subject to the deed and relevant account terms.
There is a material exception for money deposited through some third-party payment providers: it can take a few days to reach the trust, and is outside the deed’s protection during that period. The general terms also describe an exception where a licence requires a separate non-set-off account. A broad High Protection label should therefore be read with those conditions.
This concerns what happens to customer money if a gambling business becomes insolvent. It does not insure gambling losses, settle a disputed game result or remove the conditions for withdrawing an available balance. The Gambling Commission explains what different funds-protection categories mean.
What checks can affect an account or withdrawal?
The Gambling Commission requires age and identity checks before gambling. It also says an operator cannot make a withdrawal conditional on supplying information it could reasonably have requested earlier, although a legal obligation can justify a request at that stage. Paddy Power’s right to carry out checks is not a finding that every delay is justified.
Paddy Power’s document guide distinguishes UK proof of address from its Irish requirements. For UK customers it lists one utility bill or bank statement less than six months old, with other specified alternatives. Photo ID and proof of address must be separate documents. Proof-of-ID uploads use JPEG, JPG or PNG rather than PDF or screenshots; proof-of-address uploads can include PDF and qualifying screenshots.
That guide aims to review submitted verification documents within four hours, but says some cases take up to 24 hours and gives opening hours of 7am–2am. This is a document-review aim, not a maximum for every financial or account investigation and not a withdrawal-payment time.
Use the operator’s official verification channel and keep the request date and description. If a financial check is involved, ask what evidence is needed and how the request affects the balance. Our explanation of casino identity checks covers the difference between routine verification and later questions about funds.
Fees and inactive accounts
The general terms say Paddy Power does not charge for deposits or withdrawals, while banks or payment providers may charge. There is a qualification in the standard-bank-transfer guide: exceeding the displayed daily transfer limit can cause a rejection and a fee. Pay by Bank’s own page says it has no fees. Ask about the selected route if a charge is displayed.
Paddy Power’s inactive-account help says there is no inactive-account fee. Dormancy and account closure are separate matters: retain your records and check the account terms if you leave money unused.
You do not need to gamble to avoid an inactivity fee that is not charged. If you no longer want the account, request the remaining balance and use the closure process. Keep the payment and closure records.
If you want to stop gambling, use the appropriate exclusion tools rather than simply leaving an account unused. Our GAMSTOP guide explains multi-operator self-exclusion. Do not treat another brand as a workaround.
What does the regulatory history show?
On 17 December 2025 the Gambling Commission published a £2 million regulatory settlement covering four licensees trading as Paddy Power and Betfair. PPB Entertainment Limited was among them, alongside PPB Counterparty Services Limited, Betfair Casino Limited and TSE Malta LP. The findings concerned social-responsibility and customer-interaction failures identified through the 2024 assessment.
That is a total settlement across the four named licensees, not £2 million for each company or compensation awarded to each customer. PPB GE Limited and PPB Games Limited were not among the four named in that statement. The case matters to an assessment of the brand; it should not be reassigned to every group entity.
A separate announcement on 25 May 2023 concerned a £490,000 fine for PPB Counterparty Services Limited after marketing notifications were sent to devices linked to self-excluded customers. It was a different case and entity scope.
An active licence and a history of regulatory action can both be true. The current register check does not erase the published findings, and an older finding does not by itself establish what happened on your account.
How do you raise a payment or game dispute?
Start with Paddy Power customer service and state the outcome you want. For a payment, include its amount, method, request date, transaction reference and the timescale shown on confirmation. For a game, retain the exact title, round reference, account history and relevant rules. Avoid sending a full card number or identity documents through public comments or third-party review sites.
- Ask customer service to record the issue and retain the chat or email.
- If unresolved, request escalation to the complaints team and obtain a complaint reference.
- Keep the final response. Paddy Power’s UK help says acknowledgement is within 24 hours and it aims for an initial response within 10 working days, with up to eight weeks for its final response.
- For an eligible unresolved gambling-transaction dispute, follow the route to IBAS. The UK complaints code names IBAS as the approved ADR; the help page’s eCOGRA reference is labelled for non-UK customers.
The April 2025 UK complaints code describes escalation after a final response. The Gambling Commission’s complaints guidance also allows referral to the operator’s ADR after eight weeks without resolution. ADR suitability depends on the dispute; the Commission itself does not decide individual gambling-transaction complaints.
What should you confirm before depositing?
- The exact Paddy Power domain and the company for the service you plan to use.
- The deposit floor, withdrawal floor and destination for your intended payment method.
- Whether the timing describes a first use, an eligible card, a bank transfer or a later Pay by Bank withdrawal.
- Any remaining net deposits on other payment methods, document requests or account restrictions.
- The exact game rules and any separate offer conditions you choose to accept.
- A spending limit you can afford to lose, with no reliance on a future win or fast withdrawal.
Use those answers to compare another documented GB service if a payment route or condition does not suit you. There is no need to accept a promotion or make a deposit simply to complete the comparison.
What this review checked
This is a review of public records and published conditions consulted on 4 November 2026. We matched UKGC permissions and domain records and read Paddy Power’s own general and additional gaming terms, payment help, Trust Deed and UK complaints policy.
We did not open or fund an account, place a bet, test a withdrawal or contact support. We have not verified the current logged-in game library, a live offer or your account’s access. Payment details can depend on the cashier, bank, country and individual checks. Check the latest applicable terms before relying on a condition.
Related questions
Is Paddy Power Casino licensed in Great Britain?
Yes. On 4 November 2026, the three casino companies above had Active remote Casino permission and listed www.paddypower.com as Active.
What is the Paddy Power Casino minimum deposit?
The published bank comparison gives £5 for Pay by Bank and £30 for standard bank transfer. Those are route-specific figures. We have not established a universal card, Apple Pay or PayPal deposit minimum from the text reviewed; check the selected method in the cashier.
Can you withdraw from Paddy Power using Apple Pay?
The withdrawal help says yes, using a card previously used to deposit through Apple Pay on that Paddy Power account. Availability, net-deposit routing and any account checks still matter. This does not establish a single withdrawal time for every Apple Pay card.
Does Paddy Power charge an inactive-account fee?
Its published inactive-account help says no. Leaving money unused and closing an account are separate matters; retain records and check the applicable account terms.
Does High Protection guarantee all of my money?
It describes the operator’s insolvency-protection arrangement, not insurance against gambling losses or a decision on a payment dispute. Some third-party payments are outside the trust while in transit, and the deed and account terms still apply.