What is the difference between a bank transfer and open banking?
Bank transfer describes moving money between accounts. Open-banking payment initiation describes an authorised provider helping initiate a bank-account payment. One names the money movement; the other describes a way of authorising and initiating it. Neither establishes a particular casino’s support by itself.
| Label or service | What to establish |
|---|---|
| Manual bank transfer | The current recipient details, required reference and exact route supplied by the verified operator |
| Pay by Bank or instant bank transfer | The actual provider, supported bank and authorisation instructions |
| Payment initiation service, or PIS | The payment being authorised and the provider’s relevant permission |
| Account information service, or AIS | Which account information is shared, why, and under which consent |
| Wire transfer | Which country, service and transfer type the speaker means |
The FCA distinguishes a payment initiation service provider, or PISP, from an account information service provider, or AISP. A payment and permission to analyse account information are different services, even when a business can offer both. Read the permissions rather than assuming every bank connection grants the same access.
This guide covers bank-funded payments to GB online casino accounts. The phrase wire money to a casino can also concern another country or a physical venue. It does not establish that a particular GB online operator accepts an international wire or requires that route.
What should you check in the authorisation flow?
Start with the verified operator’s own cashier or support information. A message containing bank details is not enough evidence of the recipient. Check the provider, amount, currency and intended payee, including any explained payment-processing company name.
The FCA says AIS and PIS require explicit consent and directs users to check the provider’s relevant authorisation or registration. That is a payment-service check. It is separate from the Gambling Commission permission needed by the gambling operator; one regulator’s record does not answer the other question.
Trustly’s public casino help illustrates the stages: select the offered payment route, choose the supported bank/account, approve using the bank’s security method, then return and wait for the merchant’s confirmation. Its page also says the merchant decides which services are available. A provider’s general capability is not proof that every casino implements it.
Read whether the requested permission concerns this payment, an ongoing arrangement or account-information access. Do not give banking security details to HowToCasino or an unverified support contact. If the screen, payee or requested permission is unexplained, stop the payment process and verify it through independent official routes.
What do current GB operator pages actually confirm?
These are attributed public-document examples consulted on 30 October 2026, not account tests, recommendations or a complete directory. The options shown after login can depend on the customer’s bank, territory and account status.
| Published example | What its public help says | What remains separate |
|---|---|---|
| Grosvenor Casinos payment-method page | Instant Bank Transfer is listed for deposits and withdrawals; the displayed GBP minimum is £5 in each direction | Approval, account checks and the operator’s withdrawal-routing policy |
| Sky Vegas payment-change help | Pay by Bank is listed among replacement methods after PayPal and Google Pay were removed | The particular account’s supported bank, verification requirements and available alternatives |
| Sky Vegas withdrawal help | Pay by Bank is described as a withdrawal method with a £5 minimum | Whether the individual request is eligible, approved and received |
Grosvenor says deposit crediting occurs immediately upon approval. Approval is a condition, not a time measurement. Sky’s help uses instant language for its bank route; this guide does not turn that wording into a guarantee for every account or the complete request-to-bank process.
Sky’s payment-change page also describes a new-method deposit step before withdrawal. Treat that as an attributed account-policy issue, not a general instruction to pay more money to release funds. If a withdrawal is blocked by an unexpected payment demand, ask verified support to explain the requirement and available resolution; do not fund a suspicious request.
The payment-comparison guide explains why current acceptance, withdrawal eligibility and promotion eligibility need separate records. A method’s presence on an old page or another country’s version does not establish current GB support.
Why can an instant bank route still leave a pending casino payment?
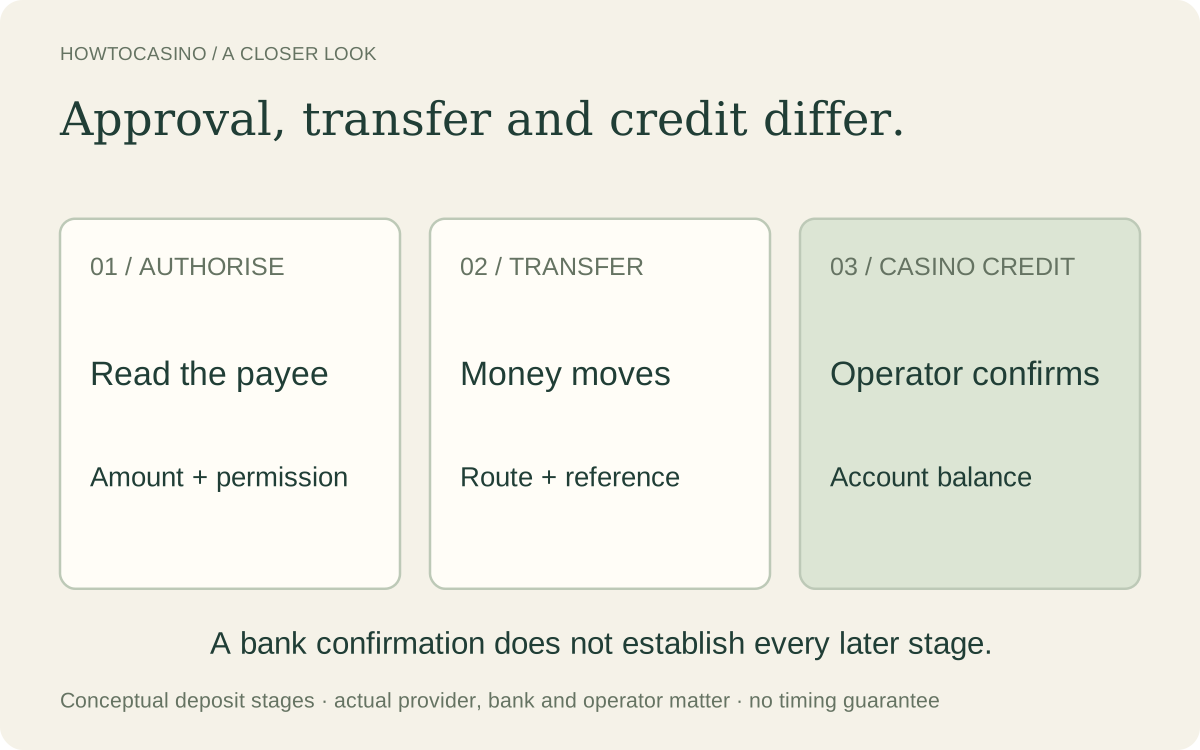
The stages answer different questions: did you authorise the instruction; did the bank send or receive money; did the provider report completion; and did the operator reconcile and credit the correct account? A confirmation at one stage should not be substituted for every later stage.
Faster Payments is a UK payment system, not the name of every Pay by Bank product. Pay.UK says payments between direct participants are usually available almost immediately and can sometimes take up to two hours. That description of the payment system is not a promised casino credit or withdrawal-completion deadline.
For withdrawals, the operator first has to decide and send the request through an available route. Trustly explicitly says the merchant determines whether its withdrawal service is available and when a request is sent. The clock for a transfer already sent is therefore not the same as the clock from pressing Withdraw.
Record the actual status and timestamp instead of making another deposit to see whether it works. Our withdrawal-delay guide covers the broader operator-review and provider stages. This page concerns what a bank-funded route does and what its label cannot prove.
How should you compare the amount debited, fees and casino credit?
Check the quote for each party’s charge and any currency conversion. A fee can be added to the requested amount or deducted from it. The following same-currency examples are entirely invented; no named operator or bank is said to charge these fees.
| Invented fee treatment | Requested amount | Bank-account debit | Casino credit |
|---|---|---|---|
| No fee | £50 | £50 | £50 |
| £1 charged on top | £50 | £51 | £50 |
| £1 deducted from the amount | £50 | £50 | £49 |
In the second row, £51 leaves the bank but £50 reaches the casino. In the third, £50 leaves and £49 is credited. These describe different price structures, not a missing pound in an otherwise identical transaction. Add currency conversion or another charge only if it actually applies and its basis is known.
A low or zero transfer charge does not improve a game’s odds or erase losses. A casino deposit is also not the same thing as the total subsequently staked. The account explainer includes a complete cash ledger that separates those quantities.
What if a bank payment is missing, declined or unauthorised?
- Check the bank, provider and operator statuses without repeating the payment.
- Keep the amount, currency, time and payment reference; mask account details before sharing evidence.
- Ask the bank/provider about an instruction or transfer problem, and the operator about account credit or a withdrawal not yet sent.
- Use verified support and the appropriate complaints process if the status remains unresolved.
- Contact your bank promptly if you do not recognise or did not authorise a transaction.
The FCA directs users with an unauthorised payment to contact their bank even if a PIS may have been used. The facts determine the applicable process and rights. A lawful losing wager is not automatically an unauthorised transfer or a reason for a gambling-loss refund.
A declined or restricted payment is not an invitation to change labels, banks or providers to evade a control. The credit-card rule applies to gambling payments made by credit card, including through money service businesses. Our credit-card guide explains that rule without treating every bank transfer or form of borrowing as the same legal instrument.
Bank/provider complaints and disputes with the casino concern different services. Identify which action is disputed before choosing a route; neither an FCA permission nor a UKGC licence guarantees the outcome of an individual complaint.
Related questions
Can you wire money to a casino?
Some services accept bank transfers, but the word wire does not establish the method, territory or recipient. This guide concerns GB online accounts; check the exact operator rather than assuming an overseas or venue-specific wire process applies.
Is Pay by Bank the same as paying by debit card?
A payment-initiation route can initiate payment directly from a bank account rather than through card processing. A debit-card payment is a different route; the service’s actual supported methods still matter.
Does connecting a bank automatically share every statement with the casino?
Do not assume that. PIS and AIS describe different services with consent requirements. Read what the actual provider is requesting and how the information is used.
Does an instant deposit mean an instant withdrawal?
No. Deposit support and a fast bank rail do not establish an eligible or approved withdrawal, the route selected or the point at which the operator sends it.
Do all GB casinos support the same banks?
No universal bank-support list is established here. Check the actual provider, operator, bank and account. The named examples are dated public-document observations, not a complete acceptance survey.
Should I repeat a deposit that left my bank but is missing at the casino?
First identify the existing payment’s status and reference through verified bank/provider and operator channels. A duplicate instruction can create a second payment without resolving the first.